01 /
Customer trust context
Bring identity evidence, credential status and review needs into a scoped view. Reuse must respect purpose, permissions and the validity of the original check.
Financial services / institutional confidence
A trust infrastructure model for banks, fintechs, payment networks and insurers—connecting identity evidence, review context and institutional oversight.
Evidence across the relationship
Customer relationships evolve. Credentials expire, evidence changes and a decision made for one purpose may not be appropriate for another.
TrustProtocol connects verification, reputation and proof so institutions can preserve context across onboarding, ongoing review and partner exchange. Each institution remains responsible for its policies and decisions.
Three connected responsibilities
01 /
Bring identity evidence, credential status and review needs into a scoped view. Reuse must respect purpose, permissions and the validity of the original check.
02 /
Show signal provenance, confidence, history and expiry alongside any assessment. A score must not replace an authorised, contestable decision.
03 /
Connect policy, reviewer action and supporting proof. Partner exchange needs explicit agreements and controlled disclosure, not unrestricted access to customer records.
A governed operating model
A reference workflow for financial institutions, not a claim that a particular banking integration or compliance programme is live.
Identify the service, jurisdiction, evidence requirements and lawful basis. Explain the process and available assistance to the customer.
Apply approved checks, record their scope and provenance, and distinguish missing information from an adverse finding.
Reassess material changes and expiring evidence under policy. Keep alerts proportionate and route uncertainty to an authorised reviewer.
Record reasons and review actions, provide an appropriate correction or appeal route, and preserve evidence under the agreed retention policy.
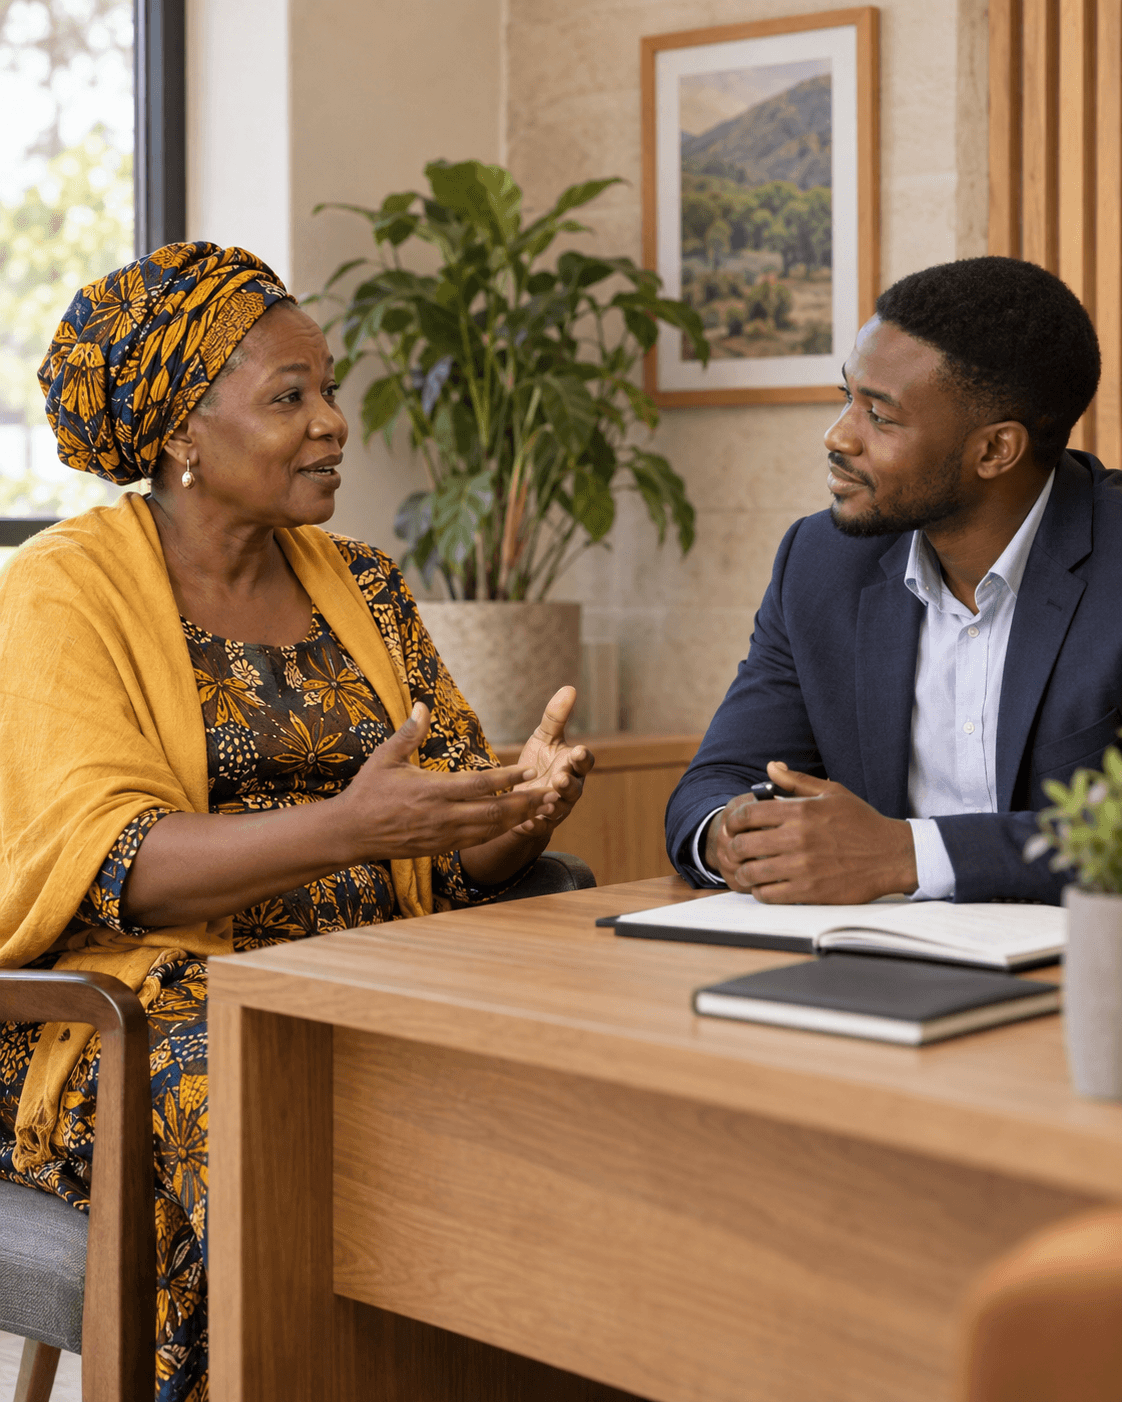
A person behind every account
Customers need to understand what is being requested, why it matters and how to correct an error. Staff need enough context to help without exposing more personal information than their role requires.
Clear explanations and human review are part of the trust model—not exceptions to it.
Institutional boundaries
KYC, AML, sanctions, retention and residency requirements need institution-specific legal, compliance and technical review. This page does not establish regulatory approval, provider coverage or a production integration.
No account opening, payment execution or automated credit decision takes place here. Deployment requires validated controls, authorised access, operational testing and a defined review path.
Explore the oversight modelDefine the use case
Map the customer journey, participating institutions, evidence boundaries and review responsibilities before selecting an integration.